Log in

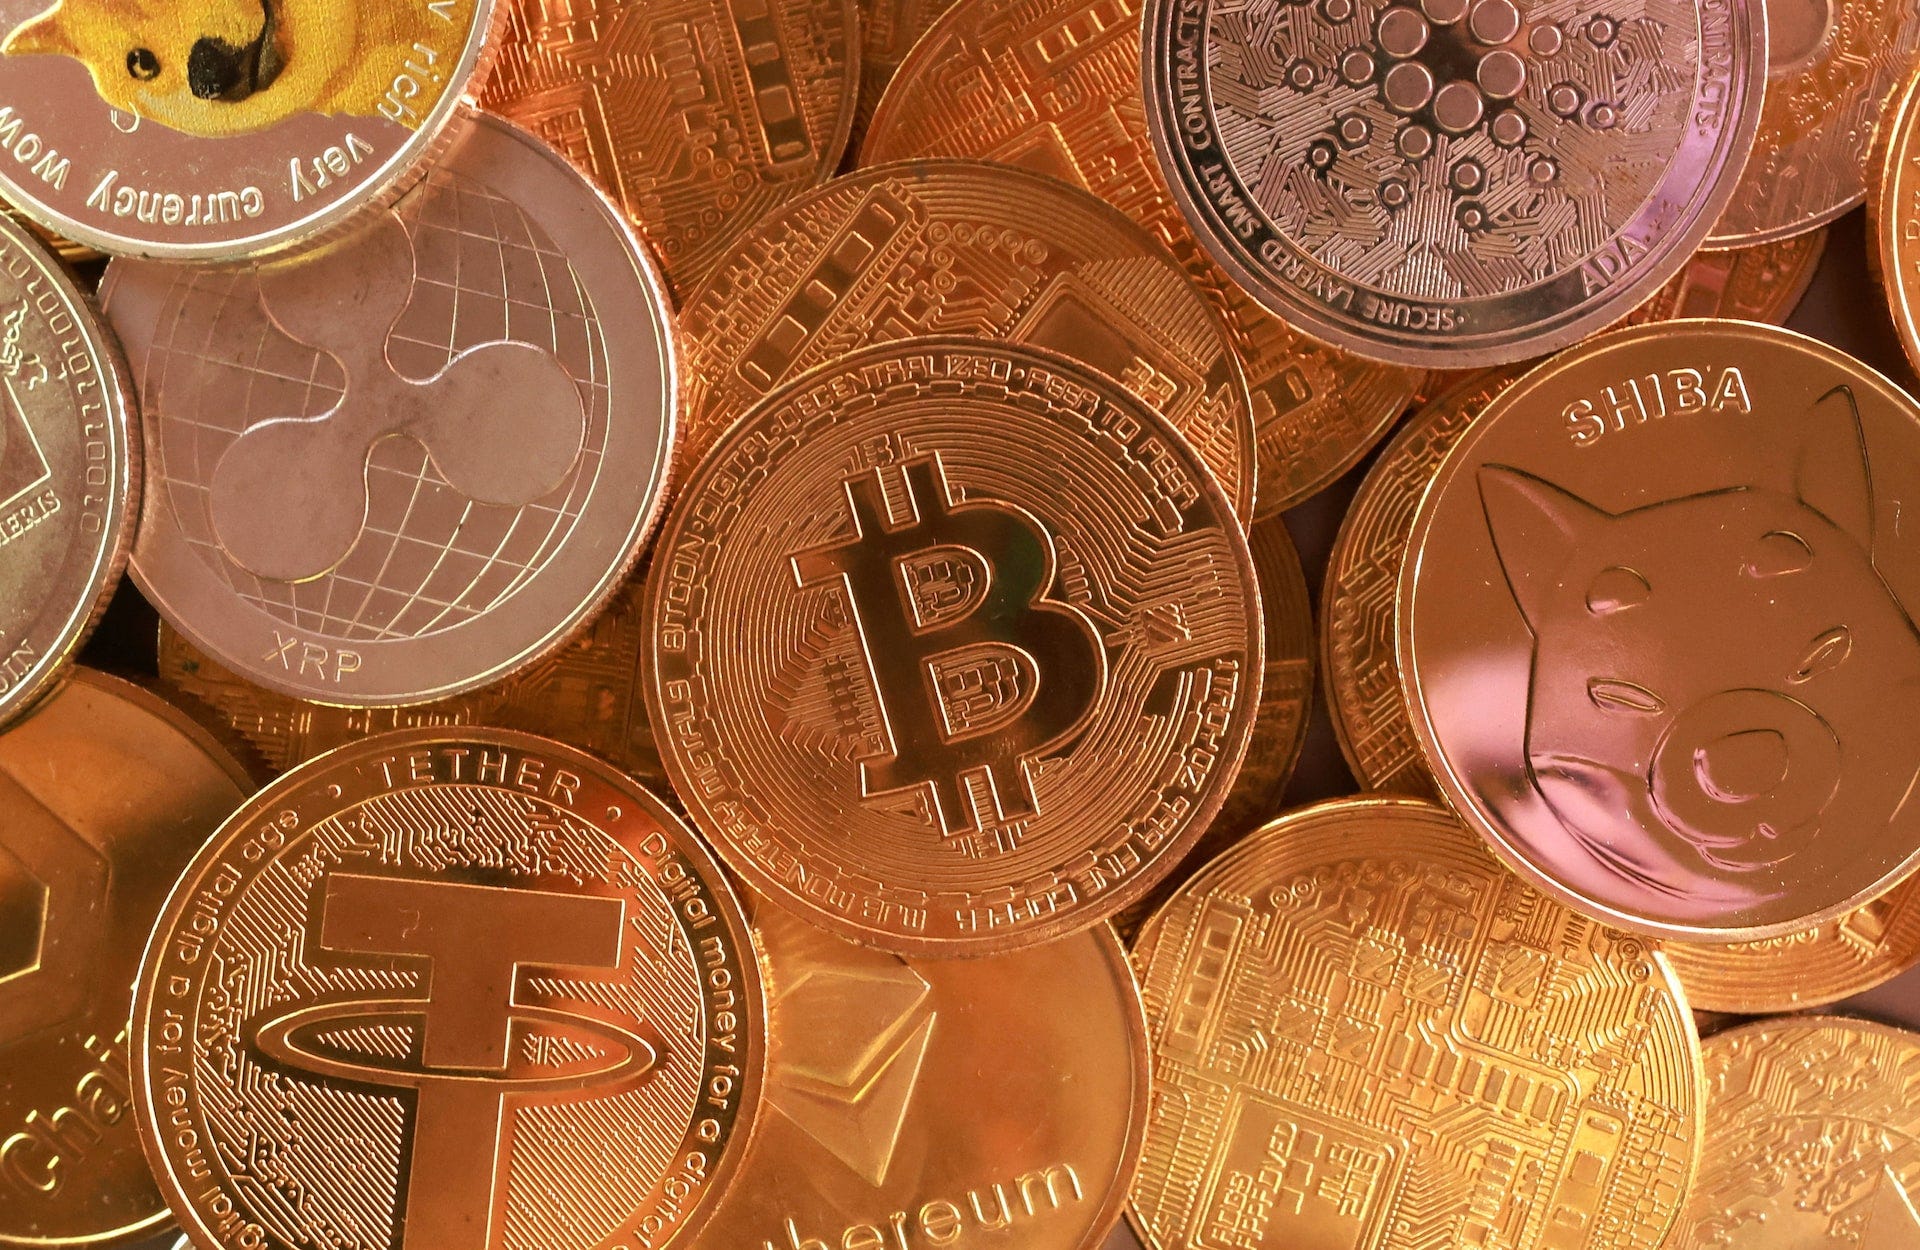
That sentence in the title is a quote from President Crypto Thug in answer to a question from a reporter asking today if he believed North Korea was behind the hack of crypto exchange Binance. Trump went on to tell the reporter, “I’ve always felt it was a little bit dangerous. But they say they have it pretty much under control. We’ll see.”
We saw, you babbling, groveling, dictator-butt-licker. Stories out today said that a team of North Korean hackers was able to use AI tools to rapidly drain $6.3 billion from Binance using “thousands of transactions in a short period...to obscure the trail of funds,” this according to a crypto analytics firm called Chainalysis.
Now, lookee here! Right away in a story about crypto we have the appearance of the word, “funds.” Aren’t “funds” supposed to be real money, as in legal tender that can be used to settle debts and buy food and hard goods such as dishwashers and mowers and clothing you can wear out of the house?
That gives us a hint of what went on with the Binance heist today. A whole bunch of people, probably in the tens or even hundreds of thousands, took real money and turned it over to Binance, which acting as an “exchange,” magically turned the people’s money into billions and billions…no, trillions and trillions…of electrons and sent them out to Arkansas somewhere where they were stored in a building that probably looks like seven Walmarts strung together, in which gigantic air conditioners and water-circulators keep the electrons from bursting into flames and just burning the whole illusory thing to the ground. It is the confusing, hellishly complicated manner of the arrangement of the electrons as blockchains that are supposed to keep the “funds” – remember them? – secure because of the “peer-to-peer” nature of the storage, using verification by “proofs” that can penetrate the blizzard of blockchains and unlock the magic of the storage method and reveal that all those electrons, or some of them anyway, actually represent “funds” that were turned over to the blockchain manager, in this case, Binance.
You will notice the complete and utter absence of anything resembling a bank in this scenario. Banks are those ancient things where you deposit money, and it is held until you want to get it out by writing a check or using a cash card to buy something. If you go into a bank and sign a piece of paper, the banks will even hold the money for you in a “savings account” or a “certificate of deposit” and pay you interest on your money for having given them the privilege of holding onto your money and earning interest on it for themselves through other manners of investment.
That ancient form of money management was deemed intrusive on your interests because the “government” could regulate what was done with your money and how you could deposit it and withdraw it from a bank. So, they invented warehouses that look like ganged-up Walmarts out in Oklahoma and Arkansas and called it “crypto” so you could store your money using electrons in blockchains with its security managed by mutual agreements about verification and secrecy concerning the methodology of penetrating the blockchains to reveal that inside them are your “funds.” Somewhere.
All of which is peachy until squads of North Koreans or somebody else get ahold of AI tools and slap them into laptops and start combing through the Great Electron Stream that is the internet looking for (1) blockchains and (2) the keys they can use to unlock them and extract…there’s that word again…your “funds.”
The great thing about the whole world of crypto for thieves is that nobody sees money anymore, as Trump, a crypto owner and user and trader and exchange manager helpfully pointed out today. That means there is no vault you have to break into using drills and dynamite charges and all the other stuff you used to see in films such as the great Michael Mann masterpiece, “Thief,” and the almost as good “The Italian Job.” Thieves can actually sit in a sweaty room in North Korea, a place where nobody can get to them, and using their fingers, they can steal billions and billions of dollars by penetrating the blockchains that supposedly protect your “funds” and taking those electrons and whisking them away into accounts in which they are stored as real dollars and located God only knows where.
This is madness, of course. Anybody who wants to store their money away in a stream of electrons deserves what’s coming to them. See also: Sam Bankman-Fried (SBF), who ran another crypto “exchange” called FTX, which was located – where else? – in the Bahamas, until it wasn’t located there anymore because he and several other of the FTX managers were indicted for taking the actual “funds” in their electron streams and fooling around with them until they disappeared, or a lot of them did, anyway.
You would think that after SBF and FTX and Bybit, another crypto exchange hacked by North Koreans for a $1.5 billion loss, that people would kind of sit back and read a few stories in the Wall Street Journal and Bloomberg and take a look and decide, you know what, I think I’ll put my money in a paper sack and keep it in the bottom of my closet with my shoes.
But you would be wrong. Crypto, it seems, will be with us for quite a while, at least until one of those multi-Walmart-looking crypto data centers bursts into flames and a whole bunch of supposedly secure blockchains burn to the ground and people’s “funds” are really, truly, gone for good.
In the meantime, Donald Trump has some shiny crypto he’s ready to sell you through his totally secure, believe me when I tell you, blockchain locker thievery-proof magic storehouse called World Liberty Financial, located – where else? – down in Florida right near Mar a Lago, so Trump and his boys can sit on their patio under their yellow-striped umbrellas and hear the crypto cooling fans whirring, just across the bay.